Table of Contents
TL;DR
Social Security is monthly retirement income, not a cash asset you add to your net worth. Your personal net worth provides savings, investments and other assets that fund the portion of retirement expenses Social Security does not cover. A clear retirement plan estimates both: dependable monthly income and the investable assets needed to close the remaining gap.
Social Security vs. Personal Net Worth: How They Work Together in Retirement
The Fundamental Difference: Income Stream vs. Personal Assets
Social Security and net worth support retirement in different ways.
Your net worth is the value of assets you own minus debts you owe. It may include cash, retirement accounts, investments, home equity and other property, reduced by mortgages, loans and credit card balances.
Social Security retirement benefits are different. They are generally monthly payments based on your earnings record and the age at which you begin receiving benefits. You do not normally add the expected lifetime value of future Social Security payments to a personal net worth calculation.
That distinction prevents two common planning mistakes.
The first is under-saving because you treat future Social Security income as though it were an investment account available today. The second is over-saving because you estimate retirement needs without counting the monthly income Social Security may provide.
A realistic plan uses Social Security to reduce the spending gap your assets need to cover, while continuing to measure your own assets and liabilities separately.
How Social Security Reduces the Portfolio You Need
Suppose you expect to spend $65,000 per year in retirement. Without Social Security, a simple 4% withdrawal framework would suggest an investable portfolio target of:
$65,000 × 25 = $1,625,000
Now assume your estimated Social Security retirement benefit is $28,000 per year. Your invested assets no longer need to cover the full $65,000 before taxes. They need to support the remaining gap:
$65,000 − $28,000 = $37,000
Using the same 25-times framework:
$37,000 × 25 = $925,000
| Retirement Planning Item | Amount |
| Planned annual expenses | $65,000 |
| Estimated annual Social Security benefit | -$28,000 |
| Annual spending gap funded by portfolio | $37,000 |
| Basic portfolio target at 25× gap | $925,000 |
Social Security reduces the investment target in this illustration by $700,000.
This does not mean $925,000 of total net worth automatically makes retirement secure. If much of your net worth is tied up in the home you intend to keep living in, those dollars may not be readily available for monthly spending. Retirement planning should focus on investable and accessible assets, along with reliable income sources.
The 25-times formula is also a starting framework, not a guarantee. Taxes, inflation, healthcare costs, investment returns and retirement length may require a larger margin.
The Social Security Claiming Decision
The Social Security Administration allows retirement benefits to begin as early as age 62. Your full retirement age, or FRA, depends on your birth year. For people born in 1960 or later, FRA is 67.
When you claim affects your monthly amount permanently.
Claiming at Age 62
Claiming at 62 gives you payments sooner, but at a reduced amount. According to the Social Security Administration, someone whose full retirement age is 67 receives 70% of their full retirement benefit when claiming at 62, a 30% reduction. Someone whose full retirement age is 66 receives 75%, a 25% reduction.
Claiming early may be reasonable when someone needs income, has limited assets to cover the waiting period, faces serious health concerns or has a shorter expected retirement horizon.
There is another issue for people still working: before full retirement age, earnings above the applicable annual limit can temporarily reduce Social Security payments.
Claiming at Full Retirement Age
Starting at full retirement age provides 100% of the calculated full retirement benefit. This can be a practical middle position for someone who wants income without accepting the early-claiming reduction, but does not want or cannot afford to wait until 70.
It is not automatically the best choice. A healthy retiree with adequate savings may benefit from waiting. Someone needing income immediately may reasonably begin sooner.
Delaying Until Age 70
For people born in 1943 or later, the Social Security Administration states that retirement benefits increase by 8% for each full year benefits are delayed beyond full retirement age, until age 70. Benefits do not continue increasing simply because you wait beyond 70.
For someone born in 1960 or later with a full retirement age of 67, waiting until 70 increases the monthly benefit to 124% of the full retirement age amount.
Delaying can be especially valuable for someone in good health who expects a long retirement, has assets to cover spending during the delay, or is the higher earner in a married household where a larger survivor benefit may matter later.
There is no universal optimal claiming age. The best choice depends on health, longevity expectations, marital situation, work plans, taxes and the assets available to bridge the gap before benefits begin.
The Break-Even Analysis
A break-even calculation asks how long someone must live before the higher delayed benefit outweighs the payments skipped while waiting.
Assume a person with a full retirement age of 67 would receive $2,000 per month at FRA. Waiting until age 70 raises the benefit to 124%, or $2,480 per month.
By delaying for three years, the person gives up:
$2,000 × 36 months = $72,000
After age 70, the delayed benefit provides an extra:
$2,480 − $2,000 = $480 per month
The simple break-even point is:
$72,000 ÷ $480 = 150 months, or 12.5 years after age 70
That places the break-even point at approximately age 82½.
This is a useful comparison, but it is not a complete claiming strategy. It does not fully account for taxes, investment returns on benefits received earlier, survivor benefits, cost-of-living adjustments or personal health. A household decision may differ from a single-person calculation.
How to Factor Social Security Into Your Retirement Plan
Begin by getting an estimate based on your own work record. The Social Security Administration provides retirement benefit estimates through a personal my Social Security account and its benefit calculators. Review projected benefits at age 62, full retirement age and age 70.
Then calculate your expected retirement spending in today’s dollars. Include housing, food, insurance, healthcare, transportation, taxes, travel and irregular costs such as repairs.
Subtract expected Social Security and any dependable pension income from annual spending. The remaining amount is what savings and investments must support.
For example:
| Annual Retirement Budget | Amount |
| Expenses | $72,000 |
| Social Security estimate | -$31,000 |
| Pension income | -$9,000 |
| Portfolio-funded gap | $32,000 |
| Basic target at 25× gap | $800,000 |
Use conservative assumptions. Social Security can be an important income foundation, but personal savings remain necessary for flexibility, emergencies, healthcare costs and the lifestyle you plan to maintain.
Tracking Your Personal Net Worth Toward the Target
Social Security may lower the amount your portfolio needs to provide. It does not replace the need to build and track personal wealth.
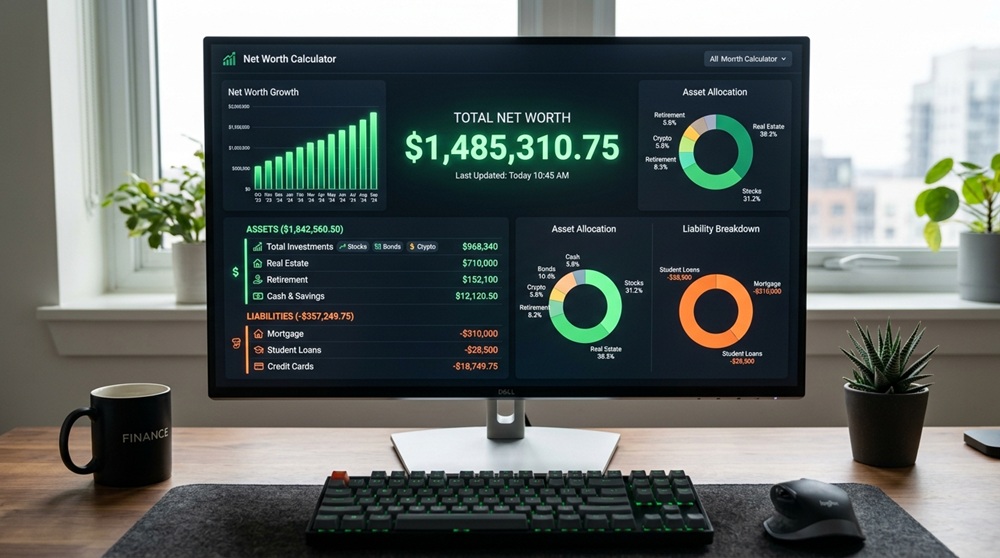
Add your current cash, retirement balances, brokerage investments, home equity and other assets, then subtract your mortgages, loans and other debts. You can calculate your personal net worth to see your current financial position, asset breakdown and debt ratio in one place.
Compare your investable assets with the portfolio-funded gap you calculated after expected Social Security income. Review the calculation at least annually, and again when your earnings record, planned retirement date, claiming age or spending expectations change.
For further practical resources on measuring financial progress and retirement readiness, visit NetlyWorth.
Social Security Is Support, Not a Complete Retirement Plan
Social Security can materially reduce the amount of personal wealth required to fund retirement. It also provides monthly income that can continue for life and is adjusted periodically for inflation.
But it is not a retirement portfolio, emergency fund or balance-sheet asset you can spend before benefits begin. Know your estimated benefit, choose a claiming strategy based on your circumstances and keep building the assets needed to fund the remaining gap. A comfortable retirement is created when reliable income and personal net worth work together.